N
Trending: AI and Credit Scoring: Balancing Inclusion with Bias Risks Hottest news
Experts debate whether artificial intelligence can improve credit decisions without deepening existing inequalities.
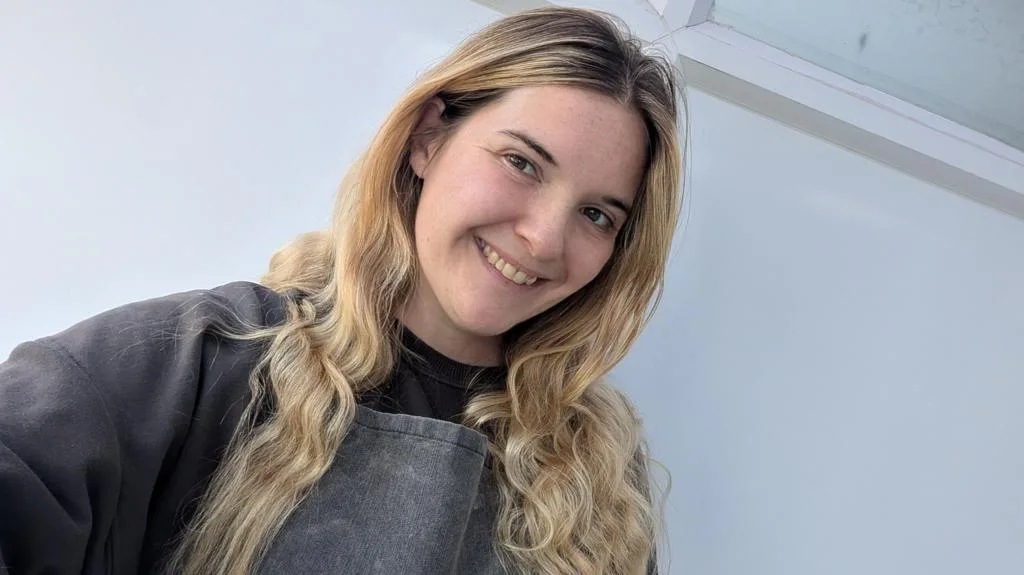 Image: BBC News Download
In November 2026, Sophie Hope, who runs a nail studio in Brighton and posts tutorials online, got a mortgage denial. She was applying for a modest £250,000 loan, but her credit score had plunged from excellent to very poor, and she blames identity theft, BBC News reports.
Traditional Scores and Their Limits
In the United Kingdom, three major agencies, Experian, Equifax and TransUnion, pull data from banks, utility bills and even telecom records. They each churn out a score from 0 to 999, using largely the same data sets. Consumer‑finance lawyer Funmi Olufunwa calls those numbers “backward looking” and warns they don’t always predict future repayment ability. Lenders still lean on them to gauge affordability, which can punish “thin‑file” applicants such as fresh graduates or recent immigrants who lack an extensive credit trail.
Hope’s story shows how a spotless record can be wiped out by fraud. “Someone opened accounts in my name on several catalogue sites and ordered a £300 PlayStation 4 and a dozen Nike socks worth about £120,” she said. The debt landed with a secondary finance firm, Bristol Finance Ltd, and sat unnoticed for three to four years before surfacing during her mortgage application.
AI‑Driven Alternatives to Legacy Models
Across the Atlantic, FICO still dominates lending, but AI‑focused firms such as Upstart and Zest AI claim to widen the data horizon. Upstart boasts machine‑learning models that chew through more than 2,500 variables, rent payments, education level, even the stability of a borrower’s job, to approve low‑cost loans. In early 2026 it funded a $15,000 personal loan for a borrower with no credit history. Zest AI leans on neural networks to spot patterns humans might miss.
Mortgage specialist Sarah Tucker, founder of The Mortgage Mum, sees AI as a way to pull together a richer picture of risk, spotting trends quickly and painting a nuanced portrait of the borrower. “It could be a real opportunity to improve financial inclusion,” she says, noting that flexible analysis might replace rigid rule‑sets.
Concerns Over Transparency and Bias
Critics demand clear explanations of the data feeding automated decisions. Tucker stresses that consumers must know which bits of information drive outcomes and retain the right to challenge mistakes.
Oxford professor Sandra Wachter warns that AI can simply echo historic prejudices if we don’t guard against bias. “Not putting any safeguards in place will fortify, foster, and enhance discrimination,” she cautions, underscoring that accountability must travel hand‑in‑hand with automation.
Upstart says it has baked bias‑detection tools into its model‑training pipeline, publishing a “Fairness Dashboard” each quarter to track improvements.
Industry Moves Toward AI Integration
The traditional bureaus are tinkering with AI too. Experian announced a partnership with OpenAI in August 2026, launching a ChatGPT‑powered portal where users can type, “Why did my score drop?” and get an instant breakdown. Equifax rolled out Equifax Amplify AI earlier this year, claiming its machine‑learning engine refines credit assessment and flags fraud faster. TransUnion revealed in March that it is weaving Google’s Gemini 1.5 models into its proprietary analytics suite.
Meanwhile, a newcomer called Noggin HQ, founded by Evangeline Atkinson and Laura Mills, offers lenders a glimpse into borrowers by analysing current‑account transaction data via a real‑time API, deliberately avoiding AI. Atkinson argues that steering clear of AI cuts the risk of embedded bias, noting that raw transaction streams could otherwise let models infer protected characteristics.
What Happens Next
BBC News notes that regulators and industry leaders are finally waking up to the flaws of purely historical scoring. The FCA has hinted at new guidelines that would require forward‑looking indicators. Olufunwa predicts credit models will soon blend past behavior with predictive signals, though she wonders whether older generations will accept the extra data collection. The future of AI in credit assessment will hinge on the balance between tech innovation, regulatory safeguards and public trust.
Further reading
For more context on this story, explore these trusted outlets.